••
Equity Risk Premium Explained: Why 5% Treasury Yields Matter for Stocks
A 5% Treasury yield raises the return hurdle for stocks. Learn how the equity risk premium is measured and what higher yields mean for stock valuations.
Share Article:
Editorial Illustration · MoneyAllotment
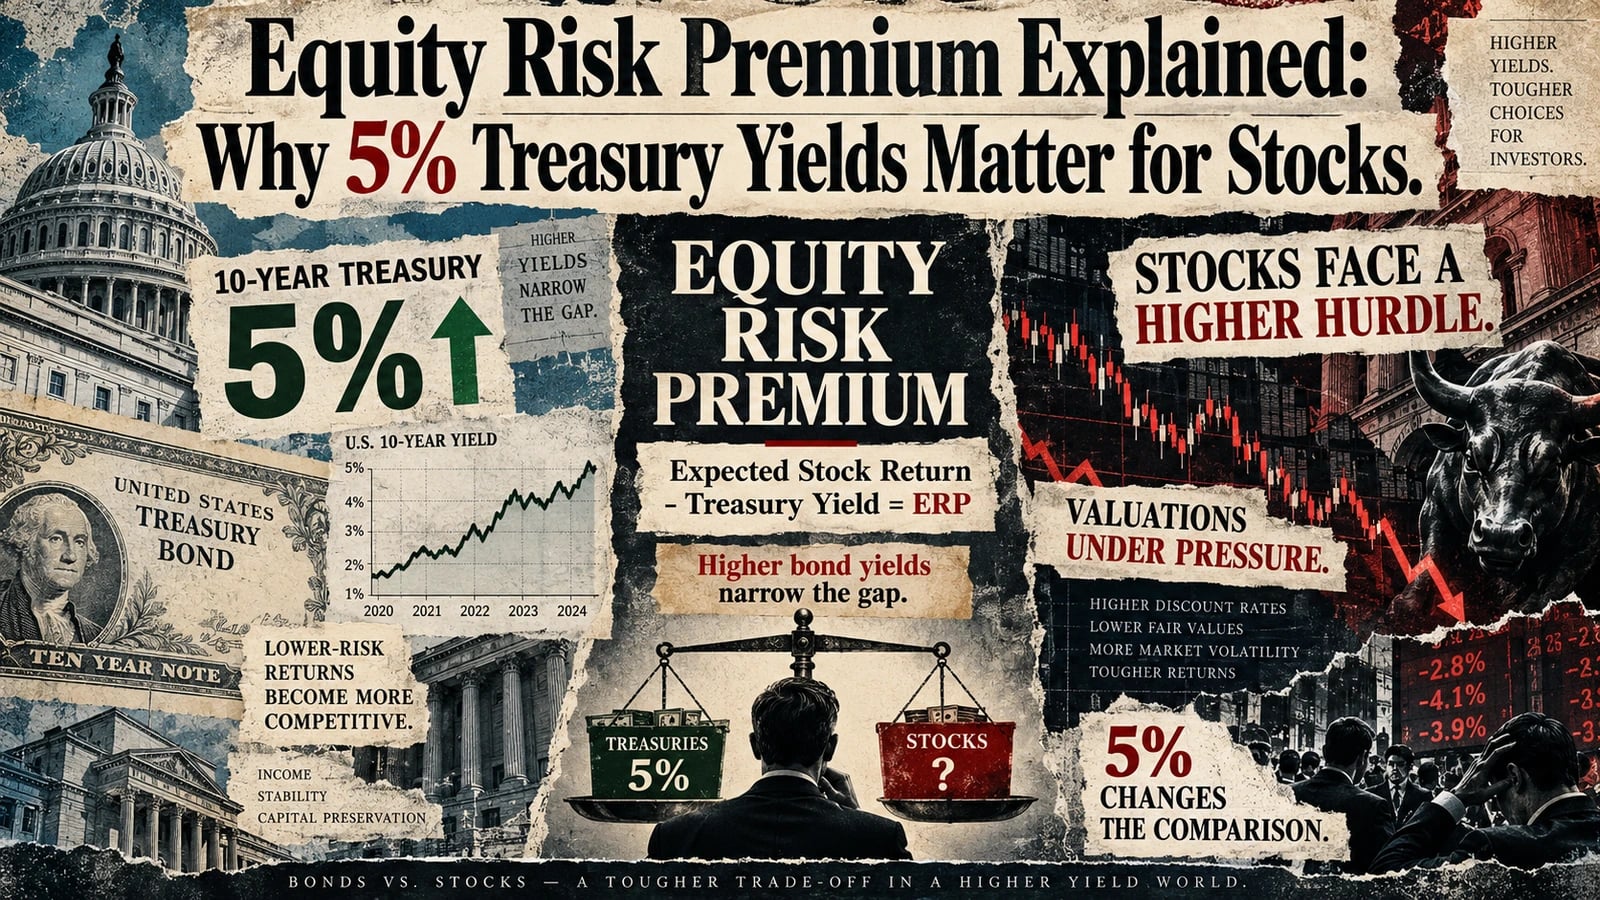
When the official 10-year U.S. Treasury par yield recorded its first close at or above 5% since 2007 in September 2026, it changed the comparison between stocks and government bonds.
A 5% Treasury yield gives investors a potentially competitive return without exposing them to the same business and market risks associated with stocks. Treasuries are not completely risk-free—they still carry inflation, reinvestment and interest-rate risk—but they create a higher hurdle for equity valuations.
The equity risk premium, or ERP, helps explain that hurdle. It measures the additional return investors expect from stocks over a relatively low-risk benchmark. The concept is simple, but the figures quoted as the “equity risk premium” can vary considerably depending on how they are calculated.
What Is the Equity Risk Premium?
The equity risk premium is the additional return investors expect to receive for accepting the greater uncertainty of owning stocks instead of a comparatively low-risk asset such as a U.S. Treasury security.
The basic formula is:
Equity Risk Premium = Expected Equity Return − Risk-Free Rate
Suppose investors expect stocks to return 9% annually while the relevant Treasury rate is 5%. The expected ERP would be:
9% − 5% = 4%
That additional 4% represents compensation for risks that Treasury investors generally do not face, including earnings uncertainty, business failures, market drawdowns and changing stock valuations.
A wider ERP means investors expect more compensation for holding stocks. It does not necessarily mean stocks are cheap. A high premium may also reflect economic uncertainty or heightened fear.
Why a 5% Treasury Yield Changes Stock Valuations
Stock values are based on the present value of the cash companies are expected to generate in the future. Treasury yields influence the discount rate used to convert those future cash flows into today’s value.
Consider $100 expected ten years from now:
- Discounted at 5%, it is worth approximately $61.39 today.
- Discounted at 9%, it is worth approximately $42.24 today.
The future cash flow has not changed. The higher discount rate alone reduced its present value.
This is why rising Treasury yields can pressure stock valuations even when companies continue to report stable revenue and earnings. As government bonds become more competitive, investors may be less willing to pay high prices for uncertain future profits.
Why Different Sources Report Different ERP Figures
There is no single universally accepted ERP number. Analysts generally use historical data, implied valuation models or a simplified earnings-yield comparison.
Historical Equity Risk Premium
The historical method compares realized stock returns with returns on Treasury bills or bonds over a selected period.
A 2025 CFA Institute contributor analysis reported an average realized U.S. ERP of approximately 6.2% from 1926 through 2024 and 10.6% during 2015–2024.
These figures describe what happened in the past. They are not forecasts of what investors will earn over the next decade.
Historical results also change depending on:
- The starting and ending dates
- Whether Treasury bills or long-term bonds are used
- Whether arithmetic or geometric averages are calculated
- The stock index selected
- How inflation and reinvested income are handled
Implied Equity Risk Premium
An implied ERP begins with current stock prices and estimates the return required to make those prices consistent with expected future cash flows.
This approach incorporates assumptions about earnings growth, dividends, share buybacks and the risk-free rate. It responds to current market conditions, although its result depends heavily on the assumptions used.
Aswath Damodaran, a professor of finance at NYU Stern, estimated the U.S. implied ERP at 4.23% as of January 2026.
Earnings-Yield Spread
Market commentary often uses a simpler comparison:
Earnings-Yield Spread = S&P 500 Earnings Yield − Treasury Yield
The earnings yield is the inverse of the price-to-earnings ratio. A forward P/E ratio of 20, for example, implies a forward earnings yield of 5%.
This spread can be useful for comparing the relative valuation of stocks and bonds, but it is not the same as a full implied ERP. It does not fully account for future earnings growth, dividends, buybacks or changes in valuation multiples.
What the September 2026 Numbers Show
In September 2026, the S&P 500 traded at approximately 19 times forward earnings, according to analyses from State Street and Goldman Sachs.
A forward P/E ratio of 19 implies a forward earnings yield of approximately:
1 ÷ 19 = 5.26%
With the nominal 10-year Treasury yield around 5%, the simplified spread between the forward earnings yield and the Treasury yield was narrow.
That did not mean the market’s complete implied ERP had fallen to zero. It meant stocks offered little immediate forward-earnings-yield advantage over nominal government bonds under that particular comparison.
The result changes when trailing earnings or real Treasury yields are used.
| Measurement | Comparison | Approximate 2026 Reading |
|---|---|---|
| Damodaran implied ERP | Expected equity cash flows versus the risk-free rate | 4.23% in January |
| Forward earnings-yield spread | Forward earnings yield versus nominal 10-year Treasury yield | Close to zero in late September |
| Trailing earnings-yield spread | Trailing earnings yield versus nominal 10-year Treasury yield | Negative in late September |
| Forward earnings yield versus real Treasury yield | Forward earnings yield versus inflation-adjusted Treasury yield | Approximately 2.7 percentage points |
These are different valuation measures and should not be treated as interchangeable.
Forward and Trailing Earnings Yields Tell Different Stories
A comparison should always state whether it uses forward or trailing earnings.
Trailing Earnings Yield
Trailing earnings yield is based on earnings reported during the previous 12 months.
GuruFocus reported a trailing S&P 500 earnings yield of 3.845% on September 24, 2026. The official 10-year Treasury par yield was approximately 5.18% on the same date.
The resulting spread was:
3.845% − 5.18% = −1.335 percentage points
Based only on recently reported earnings, the S&P 500 offered a lower earnings yield than the nominal 10-year Treasury.
Forward Earnings Yield
Forward earnings yield uses analysts’ estimates for the coming 12 months.
At approximately 19 times forward earnings, the S&P 500’s forward earnings yield was about 5.26%. That figure was much closer to the nominal Treasury yield because analysts expected corporate earnings to grow.
This comparison depends on those forecasts being reasonably accurate. If earnings disappoint, the forward yield will have made stocks appear more attractive than they were.
Why Real Treasury Yields Matter
Nominal Treasury yields include expected inflation. Real Treasury yields, commonly measured using Treasury Inflation-Protected Securities, attempt to remove that component.
State Street reported a 10-year real Treasury yield of approximately 2.6% as of September 11, 2026.
Goldman Sachs compared that figure with an S&P 500 forward earnings yield of approximately 5.3%, producing a spread of around 2.7 percentage points.
Real yields can be particularly useful when evaluating stocks because they provide a clearer view of the inflation-adjusted discount rate applied to future corporate cash flows.
When rising Treasury rates are driven mainly by higher real yields rather than higher inflation expectations, the pressure on equity valuations can be more direct.
Why Stocks Can Still Rise as Treasury Yields Increase
A narrow equity valuation spread does not guarantee a market decline.
State Street noted that the S&P 500’s forward P/E ratio declined from roughly 23 times earnings to approximately 19 times during the preceding year. At the same time, stronger earnings expectations helped support stock prices.
Investors were paying a lower multiple for each dollar of expected earnings, but the market expected companies to generate more earnings.
This creates a less forgiving environment. If companies meet or exceed those expectations, stock prices may remain resilient. If earnings growth weakens while Treasury yields stay elevated, equities may have less valuation cushion available.
Which Stocks Are Most Sensitive to Higher Yields?
The effect of rising yields is not equal across the stock market.
Long-Duration Growth Stocks
Growth companies whose expected profits are concentrated far in the future are generally more sensitive to higher discount rates.
Those distant cash flows lose more present value when rates rise. This is why highly valued growth stocks can sometimes react to interest-rate changes like long-duration bonds.
Companies With High Valuations
A high P/E ratio usually assumes strong future growth. If growth slows or the required return rises, investors may become unwilling to maintain that valuation multiple.
Heavily Indebted Businesses
Companies that depend on refinancing may face higher interest expenses as older, lower-cost debt matures.
The impact may take time to appear because many large companies borrow at fixed rates and use long maturities.
Financial Companies
Some banks and other financial businesses may benefit from higher rates through improved lending margins. The outcome depends on deposit costs, loan demand, credit losses and the shape of the yield curve.
What a Compressed Premium Means for Investors
The ERP is better used as a valuation signal than as a market-timing tool.
A narrow spread does not mean investors should sell every stock. It indicates that bonds have become more competitive and that future equity returns may depend more heavily on actual earnings growth.
In this environment, it may be useful to pay closer attention to:
- Free cash flow
- Balance-sheet strength
- Debt-refinancing requirements
- Profit margins
- The reliability of earnings forecasts
- The durability of competitive advantages
- The price paid for expected growth
Portfolio decisions should also reflect investment horizon, liquidity needs, income requirements and personal risk tolerance. One ERP estimate cannot determine the correct allocation for every investor.
Common ERP Mistakes to Avoid
Treating the Earnings-Yield Spread as a Complete ERP
The earnings-yield spread is a simplified relative-value measure. A full implied ERP includes expected future cash flows and growth assumptions.
Mixing Forward and Trailing Earnings
Forward earnings reflect forecasts, while trailing earnings reflect reported results. Combining them without clear labels can produce misleading comparisons.
Mixing Nominal and Real Yields
A comparison using a nominal Treasury yield answers a different question from one using a real, inflation-adjusted yield. The chosen measure should always be identified.
Calling Treasuries Completely Risk-Free
U.S. Treasuries are widely used as a risk-free valuation benchmark because their default risk is considered very low.
Investors can still lose purchasing power through inflation or experience losses if they sell a longer-term bond before maturity after market rates have risen.
Using the ERP to Predict the Next Correction
A low premium can persist for a long time. Earnings growth, interest-rate changes and investor sentiment can keep stocks elevated even when their relative valuation appears expensive.
The Bottom Line
A 5% Treasury yield changes the opportunity cost of owning stocks.
Investors no longer need to accept equity-market volatility simply to pursue a meaningful nominal return. Stocks must offer realistic earnings growth and sufficient potential upside to justify their additional uncertainty.
The most useful approach is to keep the measurements separate:
- Use implied ERP estimates for a forward-looking market-risk assessment.
- Use earnings-yield spreads as simplified stock-versus-bond valuation comparisons.
- Distinguish between forward and trailing earnings.
- Identify whether Treasury yields are nominal or inflation-adjusted.
A compressed spread is not a command to abandon equities. It is a reminder that when government bonds offer competitive yields, the price paid for future corporate earnings matters more.
Disclaimer: This article is for general informational and educational purposes only. It does not constitute personalized investment, financial, tax or legal advice, or a recommendation to buy or sell any security. Investing involves risk, including the possible loss of principal. Market figures and forecasts may change after publication. Consult a qualified professional before making decisions based on your circumstances.
From the Desk
All Markets →More in Markets
Strong Dollar Explained: Who Wins and Who Loses When the US Dollar Rises?
A stronger U.S. dollar can lower import costs and make overseas travel cheaper, while creating pressure for exporters, multinational companies and borrowers with dollar debt. This guide explains why the dollar rises and who benefits or loses.
Fresh Reporting
Browse All Stories →Latest from The Ledger
Credit Freeze vs. Fraud Alert: Which Protects You After a Data Breach?
A credit freeze restricts access to your credit report, while a fraud alert requires additional identity verification. Learn how they differ and which protection to use after a data breach.
Leave a Comment
Your email address will not be published. Required fields are marked *